A frozen buyer does not sit in a tender meeting thinking only about cents per kilo anymore. She is thinking about a freezer cabinet that must be full on Monday morning, a private label launch that cannot miss its slot, a shared line that handled allergens two shifts earlier, a cold store already tight before Christmas, a packaging supplier that may fail at the worst possible moment, and a recall file that must be opened before the category director starts calling. Price still matters. It always will. But in frozen food, the supplier who cannot prove capacity is beginning to look less like a bargain and more like a risk.

The tender is getting colder
Frozen food used to hide a lot of operational complexity behind a clean commercial promise. The product was stable. The shelf life was long. The retailer had time. The supplier had a freezer. Somewhere, between those assumptions, a category could be bought mostly on specification, certification and price.
That world has not disappeared, but it is thinning out. Retailers have been burned often enough to know that capacity written in a sales deck is not the same as capacity that survives a bad week. A production manager may say the line can produce 100 tonnes. The buyer now wants to know whether that means 100 tonnes of this exact SKU, in this exact bag, with this carton, this label, this allergen profile, this hardening time, this pallet pattern, this warehouse slot and this delivery window.
Those are not secondary questions in frozen. They are the product's route to the shelf.
A Capacity Passport would put those answers into a structured, versioned commercial file. It would not replace BRCGS, IFS, FSSC 22000 or retailer audits. It would sit beside them and translate operational capability into buyer language: validated line capacity, backup production, available cold storage, allergen segregation, emergency pack supply, traceability performance and incident response.
The phrase may sound new because the industry has not yet named the document properly. The need behind it is already in the room.
Private label has made capacity a brand issue
Private label growth changes the mood of supplier selection. When the product carries the retailer's name, a failure does not sit quietly with the manufacturer. It lands on the retailer's own brand. A missing retailer-brand frozen pizza, vegetable mix, potato side dish or ready meal is not experienced by shoppers as a supplier problem. It is experienced as a store problem.
Across Europe's largest grocery markets, retailer brands now account for about half of FMCG units sold. That is not a side story in procurement. It means the supply base behind private label has become part of the retailer's reputation machinery.
In a buyer meeting, the old price conversation now has harder edges. Can the supplier support a launch across several countries? Can it handle the promotional spike without stealing capacity from the base range? Can it produce the same product on a backup line if the main line fails? Can it prove that allergen cleaning is validated, not just described in a procedure? Can it show the last mock recall time?
A supplier who answers those questions quickly looks different. More expensive, perhaps. Also less frightening.
That distinction matters. In frozen private label, the cheapest supplier may still win transactional business. Strategic volume will move toward suppliers that reduce anxiety inside the retailer. Capacity becomes part of trust.
The freezer aisle exposes weak promises
Frozen is not forgiving. A chilled supplier has its own headaches, but frozen adds temperature discipline, freezing curve, storage geometry, energy exposure, condensation, freezer burn risk, dwell time, door discipline, defrost routines and refrigerated transport capacity. A small weakness in one part of the chain can become a visible gap in the aisle.
Germany is a useful reminder of scale. Frozen food sales there reached 4.238 million tonnes in 2025, and per capita consumption rose to a record 51.6 kg. This is no longer a sleepy backup category. It is daily food infrastructure, used by households and foodservice operators with the same expectation: the product should be there, it should be safe, and it should behave as promised.
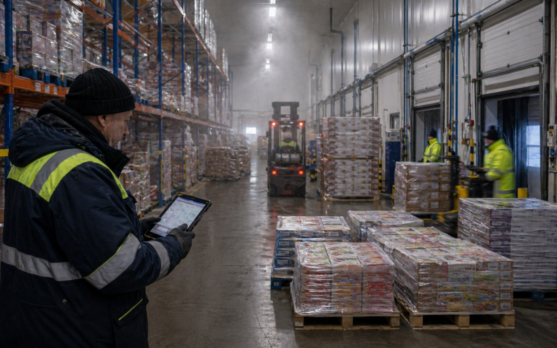
That expectation has a physical footprint. Cold storage is not an afterthought at the end of production. It is part of capacity itself. If the supplier can produce but cannot freeze, hold, pick or dispatch reliably, the commercial promise is incomplete.
In the UK, the 3PL cold storage market has been estimated at 3.4 million pallet positions, with demand exceeding supply and a large share of buildings already old. In Romania, NewCold's automated Bucharest project, planned at about 75,000 pallet positions, shows where the serious end of the market is moving: high-bay, digital, automated, measurable, built for food supply chains that cannot run on hope.
A Capacity Passport should make cold storage visible. Owned or contracted? Reserved or assumed? How many pallet positions are available in peak weeks? What are the temperature limits? Is there thermal mapping? What happens during a power incident? Are outbound slots controlled, or negotiated day by day?
These questions used to belong to operations teams. Retail buyers are learning to ask them earlier.
What the passport would actually prove
The bad version of a Capacity Passport would be a glossy PDF with factory photos, certification logos and round numbers. That would add bureaucracy without reducing risk.
The useful version would be plainer. It would show the production sites, the lines, the product families, the realistic weekly output, the actual constraint points, the pack formats, the changeover burden, the allergen status, the freezing or hardening bottleneck, the storage route, the backup option and the last time the system was tested.
For a frozen supplier, declared capacity is easy. Validated capacity is harder. A line may run beautifully on one vegetable blend and slow down on another because the piece size, moisture or pack weight changes. A potato product may be fine in standard retail bags but awkward in a promotional carton. A ready meal may be easy to produce until the sleeve format changes, or until one market needs a language correction and another needs a different nutrition panel.
The Capacity Passport would force specificity. Not "we have capacity", but "we can make this range, on this line, at this volume, with this changeover time, with these allergen controls, and with this validated backup."
Backup production deserves special attention. Many suppliers say they have another line. Fewer have another line that has already been tested for the same product family, pack size, metal detection setup, freezing route, cleaning protocol and throughput. Even fewer can say how long it takes to move the order after a breakdown and how many days are needed to recover the backlog.
Retailers should not discover the truth during a crisis. By then, every answer is late.
The awkward details buyers remember
The most important parts of a Capacity Passport are not the impressive ones. They are the awkward details that tend to break launches.
Allergen segregation is one of them. Retailers do not need another vague assurance that procedures exist. They need to know which allergens run on which lines, how production is sequenced, how cleaning is validated, how labels are reconciled, what happens to rework, and whether the packing area creates risks that the production line has already controlled. A shared line can be perfectly acceptable. A poorly explained shared line is a different commercial proposition.
Emergency packaging is another weak point. In frozen, the product can be available and still fail to ship. A film supplier misses a date. A carton arrives late. A sleeve correction is stuck in approval. A multilingual label is wrong. A promotional case format fits the retailer's shelf plan but not the supplier's packing line. Nothing about this looks dramatic from the outside. Inside the launch, it is enough to wreck a week.
A serious passport would show approved alternative suppliers for films, cartons and labels. It would show which substitute materials are technically validated, which emergency label routes are legal, how much buffer stock exists for critical components, and what temporary pack changes are commercially allowed.
There is a brutal but useful question buyers should ask: how do you fail?
Not because failure is expected on every contract. Because failure, somewhere in the chain, is normal. A supplier that has rehearsed the answer is easier to trust than one that treats every disruption as an exception.
Traceability is becoming commercial power
Traceability has often lived in the compliance drawer, brought out for audits, complaints and recalls. That is changing. European food law already treats traceability as a central food safety requirement. In the United States, FSMA 204 has pushed the industry toward additional structured traceability records for certain foods, with enforcement now not expected before July 2028. The direction is still clear: food supply chains are being asked to produce data faster, not only documents.
Frozen has its own reason to care. Long shelf life is a commercial advantage, but in a safety incident it can stretch the recall map across months, markets and intermediaries. The European Listeria outbreak linked to frozen vegetables between 2015 and 2018 remains a hard lesson. Frozen temperature does not erase microbiological risk. It preserves discipline, or it preserves mistakes.
For a Capacity Passport, traceability should not be a statement. It should be a performance measure. Can the supplier move from ingredient lot to finished goods to pallet to distribution centre quickly? Can it show mass balance? Can it block and release product without confusion? Can it run a mock recall without turning the factory office into a paper chase?
Better suppliers will start using traceability as part of the sales argument. Not as defensive compliance language after the audit certificate, but as proof that the business is under control.
The first Capacity Passports will probably be untidy. Spreadsheets, audit extracts, WMS screenshots, ERP exports, 3PL confirmations, packaging matrices, recall test records. That is acceptable. The early value is discipline, not elegance.
Later, the format will become more digital. The direction is visible in adjacent retail systems: Digital Product Passport work in Europe, richer data structures, 2D barcodes, stronger traceability expectations, more supplier scoring. A live supplier capacity profile may eventually sit beside the tender file, updated quarterly or even monthly, fed by production history, audit status, cold storage performance, mock recall results and packaging readiness.
Not every supplier will need the same passport. A small local frozen bakery specialist and a multi-country private label vegetable supplier should not face identical requirements. But the commercial direction is difficult to miss. Retailers want fewer surprises. Frozen suppliers that can prove readiness will reduce the buyer's work. Those that cannot will make the buyer investigate, verify and worry.
That worry has a cost, even when it does not appear on the quote sheet.